

تصویر Ayoob Salimipour
پروفایل پژوهشگر

Ayoob Salimipour

۲مقاله
۱کنفرانس

مقالات Ayoob Salimipour

مقاله کنفرانسی سال ۱۳۹۸ ۷۳۸ مشاهده

OPTION PRICING BY MULTILEVEL MONTE CARLO SIMULATION WITH NON-GEOMETRIC TIMESTEPS

Multi level Monte Carlo simulation that suggested by M B Giles 2008 is an efficient method for variance…

Monte Carlo simulationVariance Reduction Techniquesoption pricing
مقاله کنفرانسی سال ۱۳۹۸ ۷۵۴ مشاهده

Application of control variate technique in Asian option pricing

In this paper, we analyze variance reduction for pricing financial derivatives and we study the effect o…

variance reductionMont Carlo simulationarithmetic Asian options

حضور در کنفرانس‌ها

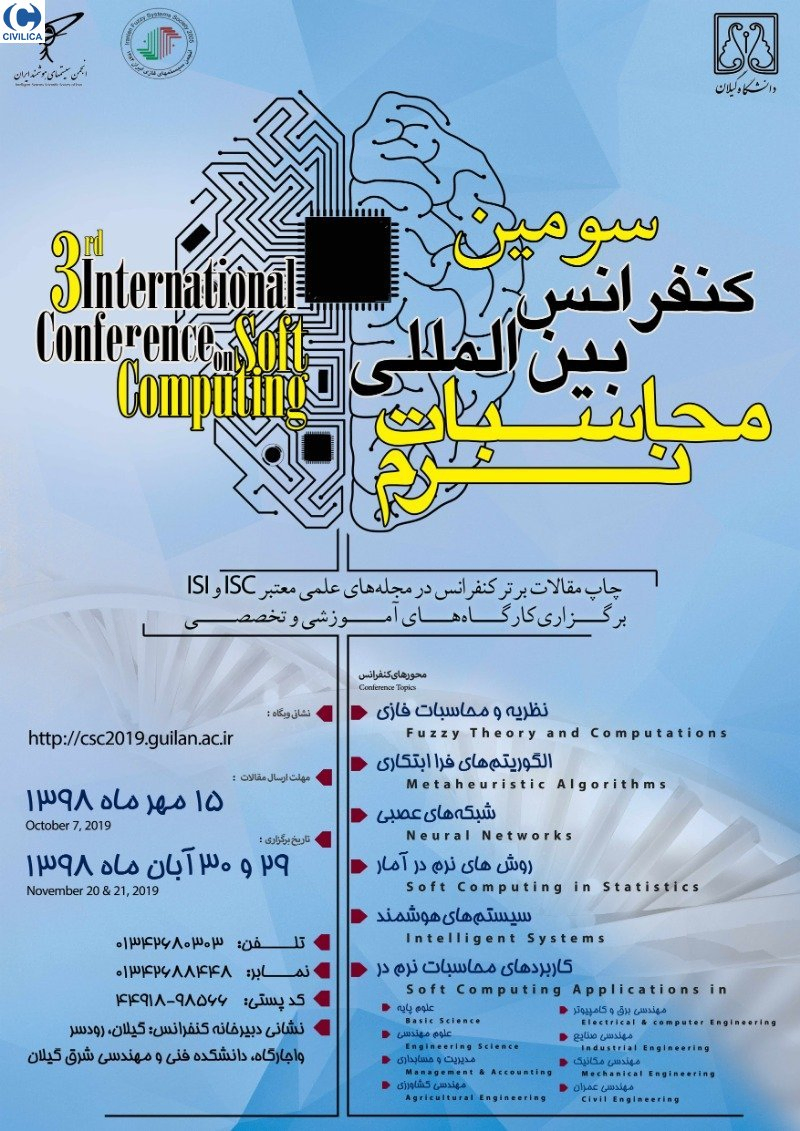
پوستر مجموعه مقالات سومین کنفرانس بین المللی محاسبات نرم
۱۳۹۸ رودسر

مجموعه مقالات سومین کنفرانس بین المللی محاسبات نرم